
Lesson B100.1 · Business 100: Start Right
Should you start? The honest math of working for yourself
7-minute read · Figures for tax year 2026
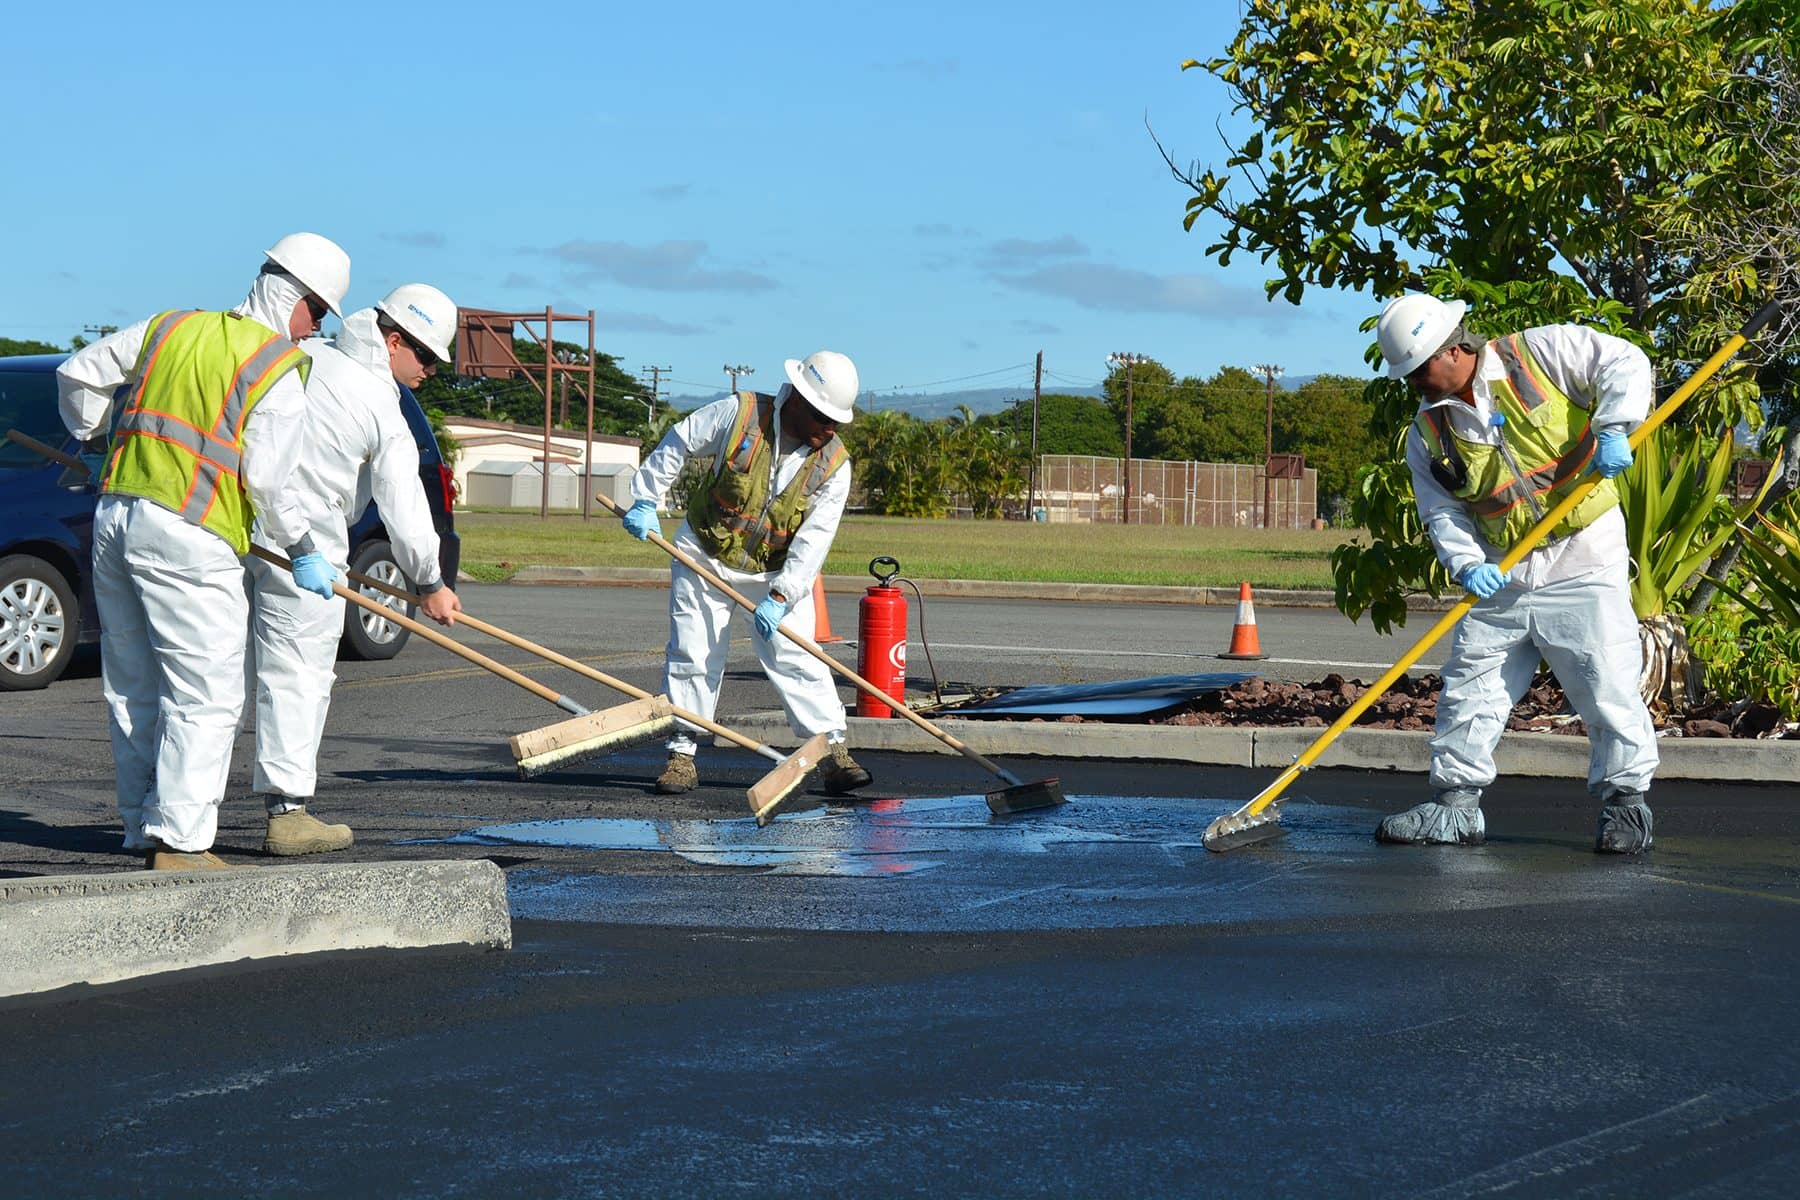
Photo: NAVFAC / Wikimedia Commons, CC BY 2.0

The short answer
Start your own pavement business only if the numbers still work after you pay both halves of Social Security and Medicare, count the days nobody pays you for, and buy the insurance, truck and equipment your employer covers now. For a lot of good people, staying employed is the right answer. If you want to try, start small and on the side, with cash you've saved, and never cash out or borrow from your retirement to do it.
What changes when you're the owner
As an employee, you're paid for the hours you work, and your employer carries the costs behind those hours. As the owner, you're paid from whatever is left after the business pays for everything else.
| As an employee | As the owner | |
|---|---|---|
| Social Security and Medicare | You pay 7.65%; your employer pays another 7.65% | You pay all 15.3%, on 92.35% of your profit |
| Taxes taken out | From every check | None; you set money aside and pay quarterly estimates |
| Rain day | Hourly crews often lose the hours | No billing, but the truck, insurance and phone bills keep coming |
| Estimates, invoices, supply runs, repairs | Paid, if you're on the clock | Unpaid, every week |
| November layoff | You can usually apply for unemployment | Self-employment income generally doesn't count toward a claim |
| Truck and equipment | The company buys and fixes them | You do, including the pump that quits in July |
| Liability, auto and workers' comp insurance | The company carries it | You buy what you need, and it's due in slow months too |
| Overtime | Time and a half over 40 hours, if you're non-exempt | None |
| Paid days off, health plan, retirement match | If the job offers them | You pay for your own |
Self-employment tax kicks in once your net self-employment earnings reach $400 for the year. You can deduct half of it.
The same paycheck, two ways
Example. Tomas, 38, is a foreman thinking about starting his own sealcoating and crack repair business. Say his job pays $40,000 a year. Example numbers only. They are not a pay guide.
| Tomas example, tax year 2026 | Stay a foreman | Go out on his own |
|---|---|---|
| Wages or profit | $40,000 | $42,270 |
| Federal tax, with Social Security and Medicare | $5,680 | $7,950 |
| Left after federal tax | $34,320 | $34,320 |
| Business costs paid first (made-up) | $0 | $30,000 |
| Work he has to sell in a year | $0 | $72,270 |
To keep the same $34,320 after federal tax, Tomas needs about $42,270 of profit. Profit is what's left after the business pays its own bills: materials, fuel, insurance, truck and equipment upkeep, phone, software and marketing. If those come to $30,000, he has to sell about $72,270 of work just to match his old paycheck. That's before he replaces a health plan or retirement match, saves for the next machine, or gets through winter.
Now count the days. Say his season runs 32 weeks, or 160 weekdays. Rain and wet forecasts take about 1 day in 5, or 32 days. Estimates, supply runs, paperwork and repairs that don't fit on rainy days and Saturdays take another 32. That leaves about 96 days to produce all $72,270 of that work.
Assumptions: single filer, 2026 federal figures, the standard deduction, no other income and no credits. The owner column includes the deduction for half of self-employment tax and the qualified business income deduction. State tax isn't included. Lesson P101.2 walks through the same math.
Staying employed is a good answer
Plenty of people build a good life on a payroll: a steady check, overtime pay, someone else's truck and a crew to lead. A strong foreman, operator or estimator has a real career, and a company that depends on them.
Dave Ramsey's EntreLeadership advice for starting a business: start small, don't borrow or cash out a 401(k) to get going, and don't go all in. If you want to test the idea, the safest way is side work while you keep your job: a few weekend driveways, a church lot on a Saturday.
Side work has its own rules:
- Keep it away from your employer's customers, and don't use company equipment without written permission.
- If you signed a non-compete or non-solicitation agreement, have an attorney read it before your first job.
- Side income is self-employment income. Report all of it, cash included, and set aside tax from every job. If you'll owe $1,000 or more for the year, you may need quarterly estimated payments, or more withholding at your day job.
Are you ready at home?
Run down this list before you spend a dollar on equipment:
- A starter cushion. At least $1,000 in savings, apart from any business money (Ramsey's Baby Step 1). How big it should grow is in the box below.
- Consumer debt handled. Paid off, or a written plan to pay it off. Every monthly payment raises what the business has to earn before your household is covered.
- A Winter Fund. A slow season that comes every year is a known expense. Once the starter cushion is in place, feed it from every in-season check, in its own account.
- Health coverage priced. If your job provides it, find out what replacing it costs before you give notice.
- Your household on board. The people you share bills with should see these numbers. Someone will keep the books at the kitchen table, take calls while you're on a lot, and hear about the customer who pays in 45 days.
Then there's the owner's real job. The trade work is only part of it. The rest is selling, estimating, scheduling, ordering materials, invoicing, collecting, fixing equipment on a Sunday and, later, hiring and leading people. Some great operators find they'd rather run work than run a company. Ask an owner you trust how many of last week's hours they actually billed.
Different approaches
Where respected teachers differ
Ramsey's Baby Step 1 is $1,000, then 3–6 months of expenses in Baby Step 3. Caleb Hammer suggests $500–$1,000 to start, then 3–6 months of essential expenses, or 9–12 months if you're self-employed. If your work is seasonal, the Winter Fund is extra, because winter isn't an emergency.
Your Move
Do this week
- Add up what you took home over the last 12 months, including overtime and any unemployment between seasons.
- Run the Work choice tool, or fill in Tomas's table with your own numbers: your pay, the profit you'd need to match it, and your honest guess at a year of business costs.
- Count your billable days: weeks in your season, minus rain, minus office and repair days.
- Sit down with whoever shares your bills and go through the numbers and the ready-at-home list together.
Log it: I ran my work-choice numbers.
Common questions
Can I start a sealcoating business while I keep my job?
Yes, and it's the safest way to start. Keep the side work away from your employer's customers and equipment, report every dollar, and set aside tax from each job.
How much do I need to make on my own to match my paycheck?
More than your wage. In the example, matching $40,000 of W-2 pay took about $42,270 of profit, and about $72,270 of sales once $30,000 of business costs were added.
Should I use my 401(k) to start a business?
No. Ramsey teaches never to borrow from or cash out a 401(k) to start a business, and this course teaches the same. That money is for the years you can't do physical work.
Watch out for
- Comparing your hourly pay with what a contractor charges. The contractor's price has to cover materials, the truck, insurance, unpaid days and both halves of Social Security and Medicare before the owner keeps anything.
- Equipment pitches built on somebody's best week. Run your numbers on a rainy one.
- Going all in at once: quitting, buying a rig and a truck, and signing payments in the same month.
- Side work on your employer's time or with their customers or equipment. It can cost you the paycheck you're counting on.
Free help
- SCORE: free mentoring from experienced business owners
- Small Business Development Centers: free one-on-one business advising
- IRS Topic 554: Self-employment tax
- IRS Tax Withholding Estimator, if side income lands on top of a paycheck
- HealthCare.gov dates and deadlines, if you'd leave job-based health coverage
Free practice
Lesson check
5 questions on this lesson, one at a time, with the answer and the reason after each. Pass with 4 right, including every must-know question.
This is general education, not tax, legal, investment or insurance advice. Rules change and every situation is different. Check the sources below, and talk to a qualified professional before you act on it.
Sources
- IRS: Topic 554, Self-employment tax
- IRS: Topic 751, Social Security and Medicare withholding rates
- IRS: Rev. Proc. 2025-32, 2026 standard deduction and brackets
- IRS: Qualified business income deduction
- IRS: 2026 Form 1040-ES, estimated tax
- IRS: Filing tips for gig economy workers
- Unemployment.gov: Unemployment benefits for contractors and the self-employed
- Ramsey Solutions: EntreLeadership: Don't risk it all
- Ramsey Solutions: Side hustle ideas
- Ramsey Solutions: The 7 Baby Steps
- Ramsey Solutions: Sinking funds
- Caleb Hammer: How much should an emergency fund be?